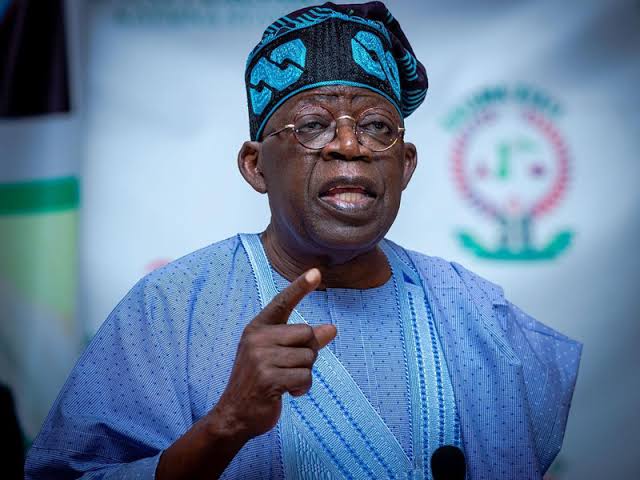
President Bola Tinubu has said the economic reforms introduced by his administration have put Nigeria on course to becoming a $1 trillion economy by 2030, despite the hardship and challenges facing citizens.
Tinubu stated this on Tuesday at the second edition of the Asiwaju Scorecard Series and Policy Roundtable in Abuja, where he was represented by the National Chairman of the All Progressives Congress, Prof. Nentawe Yilwatda.
The President said reforms implemented since he assumed office had strengthened the foundation for economic stability, growth and long-term prosperity.
Tinubu began major economic reforms on May 29, 2023, including the removal of fuel subsidies and changes to the foreign exchange market. The measures triggered mixed reactions across the country because of their varying effects on household incomes and livelihoods.
More than three years into the administration, however, the Presidency maintains that the reforms were necessary to address longstanding economic weaknesses and put the country on a sustainable growth path.
Tinubu said the removal of fuel subsidies, foreign exchange reforms, stronger revenue mobilisation and investments in critical infrastructure were designed to move Nigeria away from years of economic uncertainty.
“When President Bola Ahmed Tinubu assumed office on 29 May 2023, Nigeria faced a difficult economic inheritance. We had fuel subsidy distortions, multiple exchange-rate windows, weak revenue mobilisation, foreign-exchange shortages, rising debt-service pressures and years of inadequate investment in critical infrastructure,” he said.
“The President understood that Nigeria could not continue on that trajectory and therefore took difficult decisions, including the removal of the fuel subsidy and the reform of the foreign-exchange market.”
He said the latest economic indicators showed that the foundation was strengthening.
According to Tinubu, Nigeria’s gross external reserves rose to about $52.7 billion by August 2026, while consolidated non-oil revenue increased from approximately ₦13.63 trillion in 2023 to ₦16.4 trillion in the first two quarters of 2026.
He also pointed to an improvement in the country’s trade position, saying merchandise trade surplus rose from about ₦44.8 billion for the whole of 2023 to approximately ₦7.54 trillion in the first quarter of 2026 alone.
“Real GDP grew by 4.43 percent in Q2 2026, while inflation has fallen significantly from its earlier peak to about 15.4 percent,” Tinubu said.
“These figures do not mean that our economic challenges have disappeared, but they demonstrate that the direction of travel has changed.”
The President stressed that macroeconomic stability was only the foundation of the government’s economic agenda, saying the ultimate test would be whether the gains translate into improved living standards.
“And let me emphasise: macroeconomic stability is not the destination; it is the foundation. The ultimate test is when stability translates into cheaper food, more jobs, affordable credit, reliable electricity and greater purchasing power for Nigerians,” he said.
Tinubu said the administration’s $1 trillion economy target was not simply an economic statistic but a broader national development objective.
“Most Nigerians have asked, why the ambitious $1 trillion economy by Mr President? The $1 trillion economy is not merely a number, but a national mission: a Nigeria that produces more, exports more, attracts more investment, creates more jobs and gives its young people a greater stake in the future.”
Infrastructure At The Centre Of $1tn Plan
Tinubu said achieving the $1 trillion target would require major investments in infrastructure, with the Renewed Hope Agenda prioritising roads, railways, ports, energy and digital connectivity.
He outlined plans for an integrated five-port maritime and logistics corridor connecting major deep-sea ports in Lagos, Ondo, Ibom, Port Harcourt and Calabar.
According to the President, the ports would be linked by modern rail and road infrastructure, with the Lagos-Calabar Coastal Super Highway serving as the principal coastal road spine.
He said the Western Corridor would connect the maritime gateways to inland markets through the Lagos–Abuja–Kaduna–Kano rail corridor, alongside the Sokoto–Badagry Super Highway.
The Eastern Corridor, he added, would connect eastern maritime gateways through the Port Harcourt–Abuja–Kaduna–Kano rail corridor and the proposed Calabar–Maiduguri Trans-Sahara Super Highway.
“In this way, Nigeria can create an integrated national transport system in which our five deep-sea ports are connected to one another, connected to our major cities and production centres, and connected ultimately to the landlocked markets of Niger, Chad, Burkina Faso, Sudan and the Central African Republic,” Tinubu said.
He said the strategy would position Nigeria as a major maritime gateway and logistics hub for West and Central Africa, while increasing the country’s share of regional trade, manufacturing and distribution.
“That is more than transportation infrastructure, but a trade architecture. It would generate opportunities in logistics, warehousing, freight forwarding, customs, banking, insurance, manufacturing, distribution and agro-processing. It would create jobs, generate foreign exchange and strengthen Nigeria’s position as a regional commercial hub.”
Tinubu also called for industrial parks, export-processing zones, logistics hubs, agro-processing clusters and manufacturing centres to be developed along major transport corridors.
“Every container through a Nigerian port is an economic opportunity. Every Nigerian agricultural product exported is an opportunity. Every factory established along a transport corridor is an opportunity. Every international company that chooses Nigeria as its African distribution base is an opportunity,” he said.
“That is how we grow GDP, create jobs, earn foreign exchange and build the foundation of a $1 trillion economy.”
Energy And Youth Investment
The President said the economic transformation plan would also depend on reliable energy, highlighting Nigeria’s gas resources and the strategic importance of the Ajaokuta-Kaduna-Kano gas pipeline.
He said the AKK Project would help connect gas resources to major population and industrial centres in Northern Nigeria, supporting electricity generation, fertiliser production, manufacturing and industrialisation.
Tinubu also highlighted government programmes targeting young Nigerians, including the Nigeria Education Loan Fund, technical and vocational education initiatives and digital skills programmes.
“We are investing in the future of our young people because they are the greatest asset of the Nigerian economy,” he said.
He added that initiatives such as CREDICORP were expanding access to responsible credit for workers, entrepreneurs and businesses seeking to acquire productive assets, expand operations and create jobs.
“This is not simply social investment; it is an investment in the productive capacity of Nigeria and in the young Nigerians who will ultimately build and drive our $1 trillion economy.”
Tinubu said economic growth must ultimately improve the quality of life of Nigerians.
He said the next phase of the Renewed Hope Agenda would focus on creating more jobs, expanding access to affordable credit, lowering inflation, improving electricity supply, increasing production and strengthening the purchasing power of citizens.
Author